


Cheapest Insurance for a Rebuilt Title: What It Costs and Insurers That Cover It (2026)
May 8, 2026
Short answer: Yes, you can insure a rebuilt title car, and competitively priced full coverage is findable if you shop around. Requirements and pricing vary by company, by state, and even by agent, so two or three quotes is the whole game. The smartest money move happens before the quote, though: pay a fair rebuilt-market price for the car. Insurers base payouts on the car's rebuilt value, so when you buy at that value, a claim check matches what you actually spent. Knowing that fair number is exactly what a ReVroom Report is for.
Shopping for car insurance is already a bit of a puzzle. Add a rebuilt title to the mix and you may reach an agent who has never quoted one. The good news: rebuilt title cars are insurable, and more insurers cover them than most people think. The catch is that coverage types, requirements, and prices vary from one carrier to the next, so this guide breaks it down so you can stop guessing and start driving.
Table of Contents
- How insurers view rebuilt vs. other titles
- How much does rebuilt title insurance cost?
- Is it hard to get insurance on a rebuilt title?
- Top insurance companies that accept rebuilt titles
- What documentation and steps you’ll need
- Liability vs. full coverage: choosing what fits your budget
- When liability-only is the smart choice
- Get more expert tips on rebuilt title insurance
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Rebuilt vs. salvage matters | Insurers write standard policies on rebuilt titles (repaired and state-inspected), not on unrepaired salvage cars. |
| Liability is easy to get | Liability coverage is available from essentially every insurer for a rebuilt title car. |
| Full coverage is findable | Shopping two or three carriers usually turns up competitively priced collision and comprehensive; some ask for a quick inspection first. |
| The cost gap is usually small | Quotes are commonly reported from about the same to roughly 10 to 20 percent above a clean-title quote; the purchase discount on the car is far larger. |
| Pay the fair price first | Payouts run on rebuilt-market value, so buying at that value keeps a claim check in line with what you spent. |
| Documentation helps | Repair records, the inspection report, and a clean rebuilt title make a car quick and easy to quote. |
| Shop around for the best rate | Comparing quotes from a few insurers is the single best way to save. |
How insurers view rebuilt vs. other titles
Short answer: the state inspection is what opens the door. Before you call a single agent, it helps to understand the language. A rebuilt title means a vehicle was previously declared a total loss, then professionally repaired and re-inspected until it met state road-safety standards. That re-inspection is the turning point, because it is what separates a rebuilt title from an unrepaired car that has not yet been fixed and retitled. Those unrepaired vehicles carry a different designation, and most standard insurers write policies once repairs are complete and the title is updated.
This distinction shapes your coverage options. As Credit Karma explains, rebuilt title vehicles are insurable, with underwriting handled case by case. Liability coverage, which pays for damage you cause to others, is available essentially everywhere. Collision and comprehensive, which protect your own car, are findable too, sometimes after a photo inspection to confirm the repairs.
Details vary by state. According to Insurance Navy, results depend on how the title is branded and which state issued it. Knowing the exact status of your title before you call is step one.
Here is a quick breakdown of what to expect:
- Rebuilt title: Insurable. Liability is straightforward, and full coverage is findable by comparing a few carriers.
- Liability coverage: Available essentially everywhere. Meets state minimums. Most budget-friendly option.
- Collision and comprehensive: Availability and price vary by company and state; some ask for an inspection or appraisal first, which is why quotes beat assumptions.
“A rebuilt title means the car passed a state inspection after repairs. That is the detail that opens the door to the coverage a lot of people assume is closed.”
You can also read our full guide on getting insurance on a rebuilt title car before you start shopping.
How much does rebuilt title insurance cost?
Short answer: usually close to what the same car costs to insure with a clean title. Quotes are commonly reported anywhere from about the same to roughly 10 to 20 percent higher, and a few carriers come in higher still. Liability quotes move the least; comprehensive and collision vary the most, because the insurer is pricing a car it will value at rebuilt-market at claim time. Underwriting is case by case and varies by state and agent, so two or three quotes settles your number.
Here is the mental math that keeps this in proportion. Say the clean-title twin of your car quotes at $1,200 a year. A 10 to 20 percent rebuilt surcharge is $120 to $240 a year, and at some carriers it is zero. Meanwhile the rebuilt title saved you 20 to 50 percent on the purchase, which on a $15,000 car is $3,000 to $7,500 up front. Even a five-year run of the higher premium is a fraction of what the title brand saved you the day you bought.
Three things set your actual number:
- Your base rate. Driving record, location, and the car itself do most of the work, exactly as they would on a clean title. That is why the carrier that is cheapest for you on a clean title usually stays cheapest on a rebuilt one.
- Your coverage tier. Liability-only is the least affected by the brand. Adding comprehensive and collision is where carriers differ most, and where a photo inspection or repair records can bring the quote down.
- The car’s rebuilt-market value. It drives both the premium and the payout. Insurers settle claims at rebuilt-market value, so the number you paid for the car is the number that matters most.
That last point is the one most cost articles skip. The premium gap is small and shrinks with shopping; the payout gap is entirely in your hands at purchase. Pay the fair rebuilt-market price and a total-loss check matches your outlay. Overpay and no premium in the world closes that gap. A ReVroom Report shows how a car’s asking price stacks up against clean-title comparables and gives you the estimated savings, so you know the fair number before you insure.
Pro Tip: When you request quotes, ask for liability-only and full coverage on the same call. The gap between the two on a rebuilt title tells you exactly what the brand is costing you at that carrier, and it is often smaller than the gap between two carriers.
Is it hard to get insurance on a rebuilt title?
Short answer: not for liability, which is available from essentially every insurer. Full coverage takes a couple of calls: some carriers write comprehensive and collision on rebuilt titles as a matter of course, some ask for a photo inspection or the repair records first, and some decline. That spread is the whole reason three quotes beats one.
What makes it easy is showing up prepared. An agent who has never quoted a rebuilt title will say no faster than one who is handed the rebuilt title, the state inspection paperwork, and the repair invoices in a single folder. The documentation section below lists exactly what to bring. For what the conversation looks like at specific carriers, see our State Farm, GEICO, and USAA walkthroughs, and our guide to what insurance companies cover rebuilt title cars.
Top insurance companies that accept rebuilt titles
Short answer: there is no permanent list, and that is actually good news. Underwriting rules change by company, by state, and over time, so the winning move is running the same conversation past a handful of carriers rather than trusting any site's verdict on who says yes. Start with your current insurer plus two or three national carriers. Our State Farm, GEICO, and USAA walkthroughs show what each of those conversations looks like.
Whoever you call, these are the questions that separate a real answer from a shrug:
| Ask each insurer | Why it matters |
|---|---|
| Do you write comprehensive and collision on rebuilt titles in my state? | Availability varies by company, state, and agent, which is why one “no” means nothing |
| What documents would improve my options? | Repair records and the state inspection typically unlock better coverage and rates |
| How do you value the car at claim time? | Payouts run on rebuilt-market value, not clean-title value |
| What is the difference vs. a clean-title quote? | Commonly reported around 10 to 20 percent; varies widely |
Treat any list you find online, including ours, as a starting lineup, not a scoreboard. Each company evaluates your specific vehicle, state, and documentation before quoting, and the carrier that surprised one buyer with a great full-coverage rate may quote the next buyer differently.
You can dig deeper by reading the full rebuilt car insurance guide.
Pro Tip: If you want to get on the road fast, start with liability, then add collision and comprehensive. Many insurers happily expand coverage once a policy is in place.
What documentation and steps you’ll need
Short answer: the rebuilt title, registration, VIN, the state inspection report, repair invoices, and before-and-after photos, all in one folder before you call. Knowing which insurers to contact is only half the battle. Coming prepared with the right paperwork is what makes a quote fast and a rate fair. Insurers want to verify the car’s repair quality and roadworthiness, and the more organized your documentation, the smoother it goes.
According to CarInsurance.com, shop three or more insurers to compare, and come ready with your title, registration, VIN, and repair documentation. Rates can vary between carriers for the same car, which is exactly why comparing quotes pays off.
Here is a step-by-step approach to getting your application in order:
- Confirm your title status. Make sure your vehicle carries a rebuilt or reconstructed title. If it is not yet retitled, that is your first task.
- Gather your repair documentation. Invoices from repair shops, receipts for parts, and the inspection report from the retitling process.
- Compile before-and-after photos. Many insurers appreciate visual evidence of the repairs.
- Obtain a VIN report. Pull the vehicle history so you and the insurer share a clear picture of the car’s background.
- Get a professional appraisal if you want full coverage. An independent appraisal supports fair valuation for collision and comprehensive.
- Request quotes from at least three insurers. Use your documentation package for accurate quotes. Prices vary between carriers for the same vehicle.
Here is a quick reference for what each document supports:
| Document | Why it matters |
|---|---|
| Rebuilt title | Proof the car was legally retitled after repairs |
| Registration and VIN | Confirms the car is road-legal and identifiable |
| Repair invoices | Demonstrates professional work was performed |
| Inspection report | Shows the car passed a state safety review |
| Before-and-after photos | Visual evidence of repair quality |
| Independent appraisal | Supports fair valuation for collision/comprehensive |
Liability vs. full coverage: choosing what fits your budget
Short answer: both are within reach on a rebuilt title; the choice is about your car’s value and your budget, not about what you can get. Once your documents are ready and your shortlist is set, the last step is choosing your coverage level.
Full coverage is worth pursuing when you want to protect your own car, and shopping a few carriers is how you find it at a competitive price. Liability-only, meanwhile, isn’t a consolation prize. For many budget buyers it’s genuinely the smarter financial choice, especially on a car bought at a steep discount. The right answer depends on your situation.
One number matters more than any coverage debate: what you paid for the car. Insurers settle claims on the car’s rebuilt-market value, so a buyer who paid the fair rebuilt price gets a payout that matches their outlay, while a buyer who overpaid eats the difference. Settle that number before you insure, not after.
CarInsurance.com recommends a practical approach: get quotes for both, lean on your repair records and photos during underwriting, and pick the tier that fits how you’ll use the car.
When liability-only is the smart choice
Short answer: when the annual full-coverage premium runs more than about 10 percent of the car’s current value, or when you could absorb the loss of a car you bought at a steep discount. Plenty of content online treats full coverage as the only responsible choice. That framing does budget buyers a disservice. Liability-only, done deliberately, is often the sharper move. Here’s when it makes the most sense for you:
- Your rebuilt title car was bought at a significant discount, so its market value is lower and a full-coverage payout would be modest relative to the premium.
- You’re using the car primarily for daily commuting and mainly need to meet your state’s legal minimums.
- You have an emergency fund or a second vehicle and can absorb some risk.
Pro Tip: Compare the annual full-coverage premium against your car’s current market value. If the premium runs more than about 10 percent of the car’s value per year, liability-only often makes more financial sense.
The transparency factor helps here, too. When you buy a rebuilt title car through a platform that shows its documented repair history and title status up front, including photos of what the car looked like before repairs, you’re better positioned to choose your coverage confidently and to hand an insurer exactly what they want to see.
Get more expert tips on rebuilt title insurance
You’ve already done the smart thing by reading this far. Now let’s put that knowledge to work.
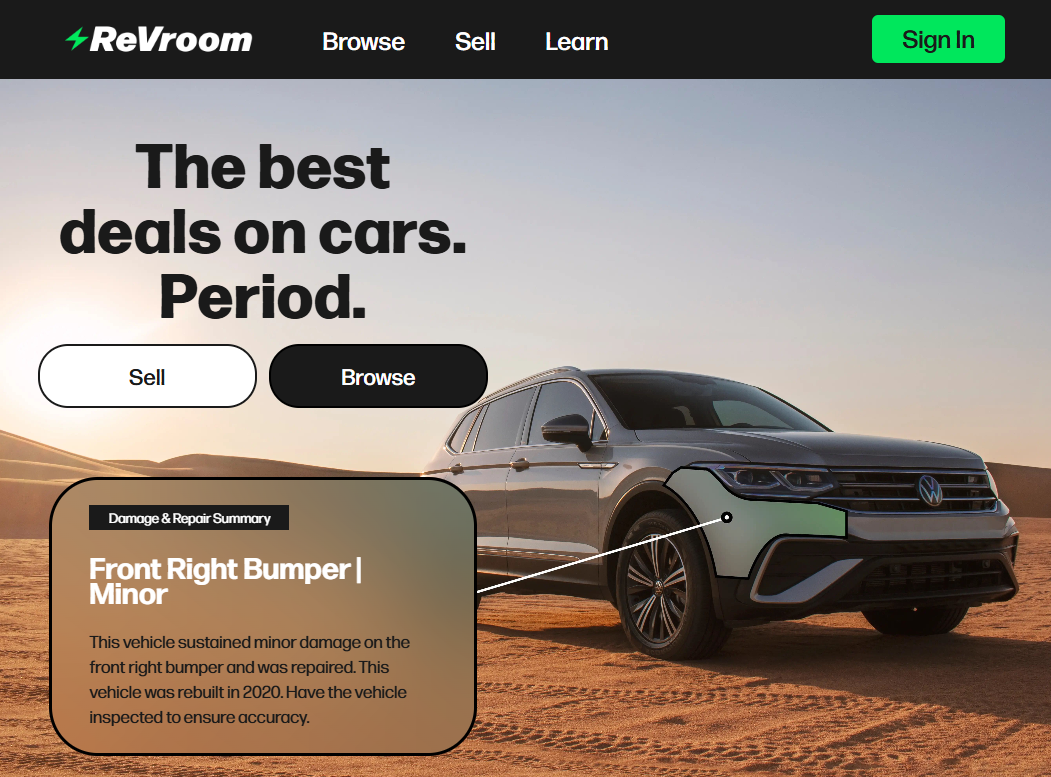
ReVroom is the marketplace built specifically for rebuilt and branded title vehicles, and every listing shows its documented repair history, title status, and photos of what the car looked like before repairs. That transparency is exactly what insurers want to see when they underwrite your policy, and a ReVroom Report shows how any car’s price stacks up against the whole market, clean-title cars included, so the price you pay and the payout you’d receive stay in line. Whether you’re ready to shop or still have questions about insuring a rebuilt title car, ReVroom has the guides, listings, and transparency to help you go further. Your budget stretches here. Your car will too.
Frequently asked questions
How much does rebuilt title insurance cost?
Usually close to what the same car costs to insure with a clean title. Quotes are commonly reported anywhere from about the same to roughly 10 to 20 percent higher, with some carriers higher still; liability quotes move the least and comprehensive and collision vary the most. On a $1,200-a-year clean-title quote that is roughly $0 to $240 a year, which is small next to the 20 to 50 percent you saved on the car itself. Underwriting is case by case and varies by state and agent, so two or three quotes settles your number.
Is rebuilt title insurance more expensive than clean title insurance?
Sometimes, and usually not by much. The base rate is driven by you, your location, and the car; the rebuilt brand adds a surcharge at some carriers and none at others. The bigger difference is at claim time: the insurer pays out on the car’s rebuilt-market value, not the clean-title value, so paying a fair rebuilt price for the car matters more than the premium gap.
Is it hard to get insurance on a rebuilt title?
Not for liability, which is available from essentially every insurer. Full coverage takes a couple of calls: some carriers write comprehensive and collision on rebuilt titles as a matter of course, some ask for a photo inspection or the repair records first, and some decline, which is why quoting three companies with your paperwork in hand works.
Which insurers are most likely to offer full coverage on a rebuilt title?
There is no fixed list, because underwriting rules change by company, by state, and over time. The reliable path is shopping: quote your current insurer plus two or three national carriers with your repair records in hand, and competitively priced full coverage turns up more often than most people expect. Our State Farm, GEICO, and USAA walkthroughs cover what to bring to each conversation.
What paperwork do I need to insure a rebuilt title car?
Most insurers will want your rebuilt title, registration, VIN, and repair documentation, plus before-and-after photos of the repairs if available.
Can you get full coverage on a rebuilt title?
Yes. Competitively priced collision and comprehensive are findable on rebuilt titles if you compare a few carriers; some ask for a quick inspection first. Liability is available essentially everywhere.
Why do insurance rates vary for rebuilt title cars?
Rates depend on the usual factors, your record, location, the car, and coverage level, plus how easily the insurer can verify the repairs. Good documentation helps you get a fair rate, and comparing quotes is the best way to save.
Who has the cheapest insurance for a rebuilt title?
Usually whoever already insures you. Rebuilt-title surcharges stack on top of your base rate, so the company that quotes you lowest on a clean title tends to stay lowest on a rebuilt one. Two or three quotes settles it.
Do any insurers refuse rebuilt titles?
Some do, and underwriting rules shift, which is exactly why shopping around works. Ask enough companies and you’ll find liability broadly available and full coverage available more often than the internet suggests.
How do I make sure an insurance payout covers what I paid?
Buy at the car’s fair rebuilt-market value, because that value is what payouts are based on. That’s the hard part when you’re shopping blind, and it’s where a ReVroom Report earns its keep: it shows how a car’s price stacks up against the whole market, clean-title cars included, so you know you’re paying the fair number before you ever call an insurer.
Already financed your rebuilt title car?
If your credit has improved since you bought, a refinance can lower the payment on the same car. One application, up to 4 offers.
See if a refinance lowers your payment →Sponsored · myAutoloan
