


Navy Federal Rebuilt Title Loan: Will Navy Federal Finance a Rebuilt Title? (2026)
July 6, 2026
TL;DR:
- Short answer: Navy Federal's standard auto loan can't be used on a rebuilt (or salvage) title. Its 2026 dealer instructions say so in writing.
- The door that is open: a Navy Federal personal loan, currently 8.74% to 18.00% APR, no collateral, no fees, funds in about a day.
- Navy Federal does not do title loans, and the famous 90-day (3-month) title rule only applies to its auto loans, so it never touches a rebuilt car bought on a personal loan.
- Up to 50% off the car usually beats a few points of extra interest. We run the math below.
Short answer: yes, you can finance a rebuilt title car through Navy Federal, but not the way most members assume. Navy Federal's published dealer instructions rule rebuilt and salvage titles out of its standard auto loan, and point members to a signature loan instead. That is Navy Federal's plain-English term for an unsecured personal loan. It costs a little more in interest, it comes with zero lien paperwork, and on a car that costs up to 50% less than its clean-title twin it is very often the cheaper deal overall. Here is exactly what Navy Federal says, what it costs, and how to do it right.
Not a member, or want a second quote? Compare offers from lenders that accept rebuilt titles with one application (up to 4 offers, as published). ReVroom is not a lender.
Does Navy Federal finance rebuilt title vehicles?
Short answer: not with its regular auto loan. Navy Federal's 2026 Preapproved Vehicle Loan dealer instructions (NFCU 478) state that the loan "cannot be used for any consumer collateral loans where the title reflects the vehicle as commercial/business, salvaged, lemon, refurbished, or rebuilt," and that "members who wish to purchase vehicles of this nature will have to qualify for the loan on signature or select another vehicle to purchase."
Read that last line twice, because it is the whole game. "Qualify on signature" means an unsecured personal loan: Navy Federal lends you the money on the strength of your credit and your membership, not on the car. The car is never collateral, Navy Federal never goes on the title as lienholder, and the appraisal-and-LTV dance that trips up rebuilt title buyers at other lenders simply never happens.
Two honest caveats. First, this is Navy Federal's published guidance as of 2026; lender policies change, so ask a loan officer to confirm before you shop. Second, "not with the auto loan" is not "no." Plenty of members finance rebuilt cars through Navy Federal every year; they just use the personal loan desk instead of the auto loan desk.
Navy Federal membership is open to active-duty, reserve, National Guard, and retired members of every branch, veterans, Department of Defense civilians and contractors, and their families and household members. You must be a member before you can apply for any Navy Federal loan, and a longer relationship with on-time history helps on a signature loan more than anywhere else, because your track record is the only collateral.
One more thing worth knowing: lenders check title status through the National Motor Vehicle Title Information System (NMVTIS), a federal database that records prior total-loss brands. A rebuilt title is not something you can hide from a lender, and you should not try. The good news is that you do not need to. Bring the title as it is and apply for the product that fits it.
Will Navy Federal finance a salvage title car?
Short answer: no, and neither will almost anyone else. The same dealer instructions list "salvaged" right next to "rebuilt" as ineligible collateral. Beyond Navy Federal's policy, a salvage title is a car that has been declared a total loss but has not yet been repaired, inspected, and cleared by the state. In most states it cannot be registered or driven, which is why lenders will not secure a loan against it.
The practical move is to skip the salvage stage entirely. Buy a car that has already been professionally repaired and retitled as rebuilt, which means it has passed the state inspection a clean-title car never has to face, and finance it with a Navy Federal personal loan. If the difference between the two titles is still fuzzy, our guide to salvage vs. rebuilt titles sorts it out in five minutes.
Does Navy Federal do title loans?
Short answer: no. A car title loan is a short-term loan from a storefront lender secured by the title of a car you already own, and Navy Federal does not offer one. Its own member education page on title loans warns that these loans "may have rates of 300% per year, or more" and suggests a personal loan as the alternative people overlook.
So if you searched "Navy Federal title loan" or "can you get a title loan with a rebuilt title," here is the translation. Navy Federal offers two things that scratch that itch: auto refinancing for eligible vehicles, and unsecured personal loans from $250 to $150,000. For a rebuilt title car, the personal loan is the one that fits: Navy Federal has not published a rebuilt-title exception for refinancing, so do not count on refinancing a rebuilt car there without asking first.
How to finance a rebuilt title car through Navy Federal: the personal loan route
Here is what the Personal Expense Loan looks like, straight from Navy Federal's rate page as of September 2026.

Loan amounts and terms
- $250 to $150,000; loans above $50,000 need a qualified co-applicant
- Fixed rate, 8.74% to 18.00% APR up to 36 months, 10.69% to 18.00% APR for 37 to 60 months, based on creditworthiness
- No collateral, no application or origination fees, no prepayment penalty
- Most decisions in seconds, most loans funded in 24 hours or less
Membership and credit profile
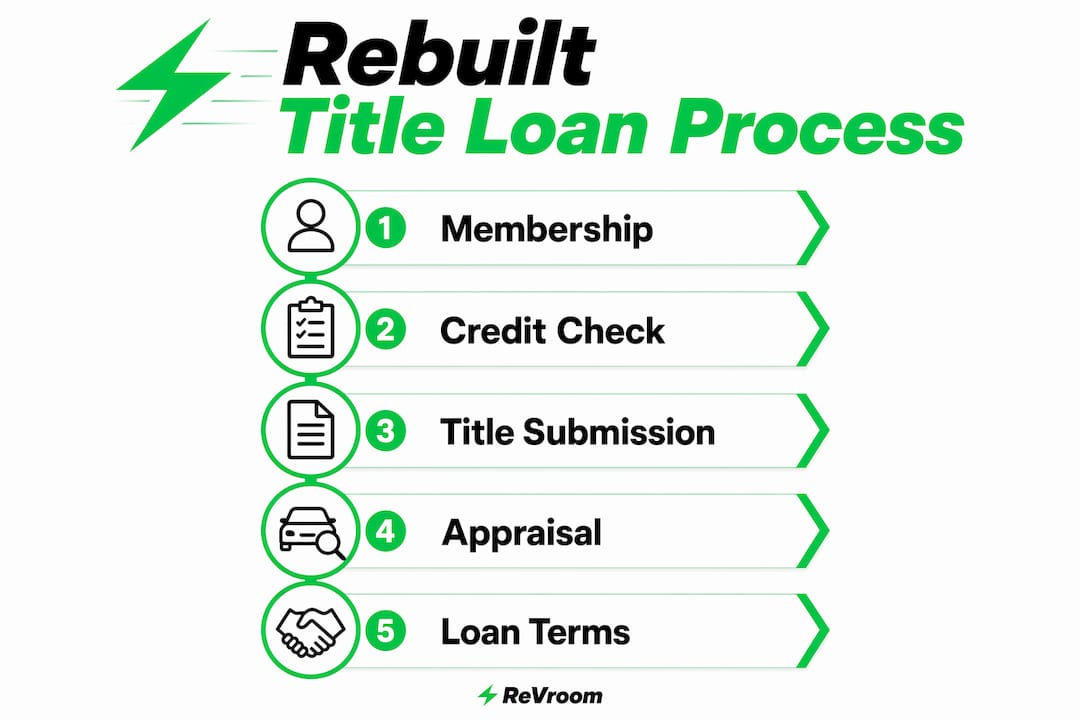
Because nothing secures the loan, Navy Federal is looking at you, not the car: credit history, income, debt-to-income ratio, and your standing as a member. Think of it as having a track record that speaks for you before you ever mention the vehicle. Members with a longer relationship and clean payment history land at the low end of the rate band; thinner files land higher or get declined, and Navy Federal's own FAQ is clear that "loan approval isn't guaranteed."
Vehicle documentation you should still gather
A personal loan does not require an appraisal or repair records, but you should collect them anyway, because they protect you, and they make the eventual resale easier:
- The official rebuilt or reconstructed title issued by your state's DMV
- Repair records showing what was fixed and by whom
- The state inspection certificate from the rebuilt retitling
- Photos of the vehicle before and after repairs, when the seller has them (every ReVroom listing shows photos of what was repaired)
What about loan-to-value limits?
There aren't any on a personal loan, because there is no lien. For comparison, Navy Federal's standard auto loan requires the vehicle to be worth "at least 100% of the amount financed" by NADA Retail Value, and lets the loan reach up to 125% of that value to cover tax, title, and tags. The personal loan skips all of it; the number that matters is simply what you can afford to repay.
Pro Tip: Ask for a little more than the purchase price so tax, title, and registration are covered in one fixed payment. Since there is no prepayment penalty, you can pay the unused part straight back the next week.
What is the 90-day (3-month) title rule, and does it apply to you?
Short answer: only if you have a Navy Federal auto loan, which a rebuilt car will not. Navy Federal's registration and titling page says that "within 3 months of purchasing or refinancing your car," a title naming Navy Federal as first lienholder must be submitted, and that if it is not received in time "your loan's APR may be converted to Navy Federal's rate for signature/personal loans, which is typically higher." Its auto loan FAQ phrases the same window as 90 days.
Notice the penalty: it is a rate conversion to the personal loan rate, not the loan being called. And notice what happens on a rebuilt car bought with a personal loan: there is no lien, so there is no title to send in and no deadline to miss. You get the title from the DMV in your own name and you keep it. For anyone who has ever chased a DMV for paperwork, that alone is worth something.
What are typical rebuilt title loan rates and terms?
Short answer: through Navy Federal, 8.74% to 18.00% APR, because it is a personal loan. That is higher than Navy Federal's clean-title used auto rates, which start as low as 4.79% APR for short terms and 5.29% to 6.98% for longer ones (rates as of September 2, 2026). It is also right around what the average used-car buyer pays anyway: Experian's Q1 2026 auto finance data reports an average used-car APR of about 11.43%, ranging from roughly 6.3% for superprime borrowers to nearly 22% for deep subprime.
Here is the comparison that matters, side by side.
| Feature | Rebuilt title via Navy Federal personal loan | Clean title via Navy Federal auto loan |
|---|---|---|
| APR range (Sept 2026) | 8.74% to 18.00% (36 mo); 10.69% to 18.00% (37 to 60 mo) | As low as 4.79% to 6.98% used, up to 18.00% max |
| Collateral / lien on the car | None; you hold the title | Navy Federal is first lienholder |
| Loan-to-value cap | None (no lien) | Car must be worth 100% of amount financed; loan up to 125% of NADA value |
| 3-month title rule | Does not apply | Applies; APR may convert to personal-loan rate if missed |
| Navy Federal GAP ($499) | Not available (auto loans only) | Available on vehicles 7 years old or newer |
| Full coverage required by lender | No lender requirement; your choice | Yes |
| Typical price of the car | Up to 50% below clean-title value | Full market value |
Two rows deserve a closer look. Navy Federal's GAP coverage is a $499 add-on sold only with its auto and motorcycle loans on vehicles no older than seven years; its GAP page does not mention rebuilt titles at all, but since the auto loan is off the table, GAP goes with it. On a personal loan the "gap" is yours to manage, and the fix is boring and effective: a real down payment.
The insurance row is a quiet win. No lender is forcing full coverage on you, but full coverage is still smart on any car you would miss. Most major insurers write rebuilt title policies; a few are pickier about comprehensive and collision, so get quotes before you commit. Our guide to which insurers cover rebuilt titles is the place to start.
Pro Tip: Get your insurance quote and your Navy Federal personal loan pre-approval on the same afternoon. Both take minutes, and together they tell you the true monthly cost before you fall in love with a car.
What are the alternatives if Navy Federal won't approve your loan?
Many national banks decline rebuilt title auto loans because their automated systems flag non-standard titles before a human ever sees the file. If your Navy Federal personal loan application is declined, you still have real options:
- Local credit unions. Smaller credit unions often use manual underwriting by default, and some will write a secured auto loan on a rebuilt title that a national bank's algorithm would never touch. Our guide on whether a bank will finance a rebuilt title covers what to ask.
- Other lenders' personal loans. The Navy Federal logic works everywhere: an unsecured loan sidesteps appraisals, LTV caps, and lien paperwork entirely. Compare rates, because the range across lenders is wide.
- Specialty lenders. A handful of lenders build their underwriting around rebuilt title valuations. Rates tend to be higher, approval odds better.
- Dealer financing programs. Dealers who specialize in rebuilt title cars usually have lender partners who accept them. Ask directly whether they offer in-house or preferred-lender financing.
- Cash. On a car that costs up to half of its clean-title value, cash is a live option far more often than people expect.
For the whole map of lenders and what each one wants, see Can you finance a rebuilt car? To compare rebuilt title loans from several lenders with one application, start on ReVroom's financing page.
Compare lenders in one step
Credit unions like Navy Federal and USAA decide case by case. A lender network compares several at once.
One application through myAutoloan, up to 4 offers within minutes. Purchase, private party, or refinance.
Get my offers →Sponsored · myAutoloan
How to finance a rebuilt title car at Navy Federal, step by step
-
Confirm your Navy Federal membership. You must be a member before applying. If you are eligible but not yet a member, join and let a little on-time history build before you apply.
-
Know your number. Pull your credit score and fix any errors. On a signature loan, your credit file is the collateral, so it is worth a week of cleanup.
-
Apply for a Personal Expense Loan, not an auto loan. Apply online, in the app, by phone, or at a branch; decisions usually take seconds. Request enough to cover the car plus tax, title, and registration.
-
Shop with the funds in hand. Most loans fund within 24 hours. Walking in as a cash buyer is a strong negotiating position, especially at a dealership used to arranging financing on rebuilt titles.
-
Do your own homework on the car. Review the rebuilt title, the inspection certificate, and the repair records. On ReVroom, filter by history type and in-house severity grade before you ever call a seller, and pull a ReVroom Report for the severity grade and market-price comparison.
-
Title it in your name and keep it. No lienholder, no 3-month clock. Register the car, insure it, and drive.
Pro Tip: There is no prepayment penalty on Navy Federal personal loans. If you took a five-year term to keep the payment low, throw extra at it whenever you can and the rate premium shrinks fast.
Key Takeaways
A Navy Federal rebuilt title loan is real, it is just a personal loan wearing a different name. The trade is a few points of interest for zero lien hassle on a car that costs up to half as much.
| Point | Details |
|---|---|
| Auto loan: no | Navy Federal's 2026 dealer instructions exclude salvaged, lemon, refurbished, and rebuilt titles from its collateral auto loan. |
| Personal loan: yes | "Qualify on signature" means an unsecured personal loan, $250 to $150,000, 8.74% to 18.00% APR, no fees, funds in about a day. |
| Salvage title: no | Same document, same list, and a salvage car usually cannot be driven anyway. Buy one already retitled as rebuilt. |
| Title loans: no | Navy Federal does not offer them and warns members about 300%-plus rates elsewhere. |
| 3-month title rule | Auto loans only; a missed deadline converts the APR to the personal loan rate. Irrelevant on a personal loan. |
| Alternatives exist | Local credit unions, other personal loans, specialty lenders, dealer programs, and cash. |
The honest truth about rebuilt title financing at Navy Federal
From where we sit at ReVroom, the biggest mistake buyers make with rebuilt title financing is chasing the lowest rate instead of the lowest total cost. Let me show you why that matters with a made-up but realistic example; your prices and rates will differ.
Say a clean-title car sells for $24,000 and its rebuilt-title twin, same year, same trim, professionally repaired and state-inspected, sells for $12,000. Finance the clean car at Navy Federal's 5.29% used auto rate over 48 months and the payment is about $556, roughly $26,700 paid over the life of the loan. Finance the rebuilt car on a Navy Federal personal loan at 12% over the same 48 months and the payment is about $316, roughly $15,200 all in. The "worse" rate saves you around $11,500 and $240 a month, and you own the title outright from day one.
That is the part the rate comparison sites miss. A rebuilt title is a discount on the car's past, not its present. The one variable that actually matters is repair quality, which is why we grade every car's history in-house, from hail and cosmetic paint chips all the way to fire recoveries, and let you filter to the severity you are comfortable with. No other marketplace lets you do that.
Start with your Navy Federal relationship and the personal loan desk. If that door closes, walk into your nearest local credit union and ask for a loan officer by name. The personal relationship still counts in this corner of the lending world.
— ReVroom Editorial Team
Rebuilt title vehicles worth financing: find them on ReVroom
Financing a rebuilt title vehicle starts with finding the right car. That part is harder than it sounds when you are shopping general marketplaces with no history context at all.
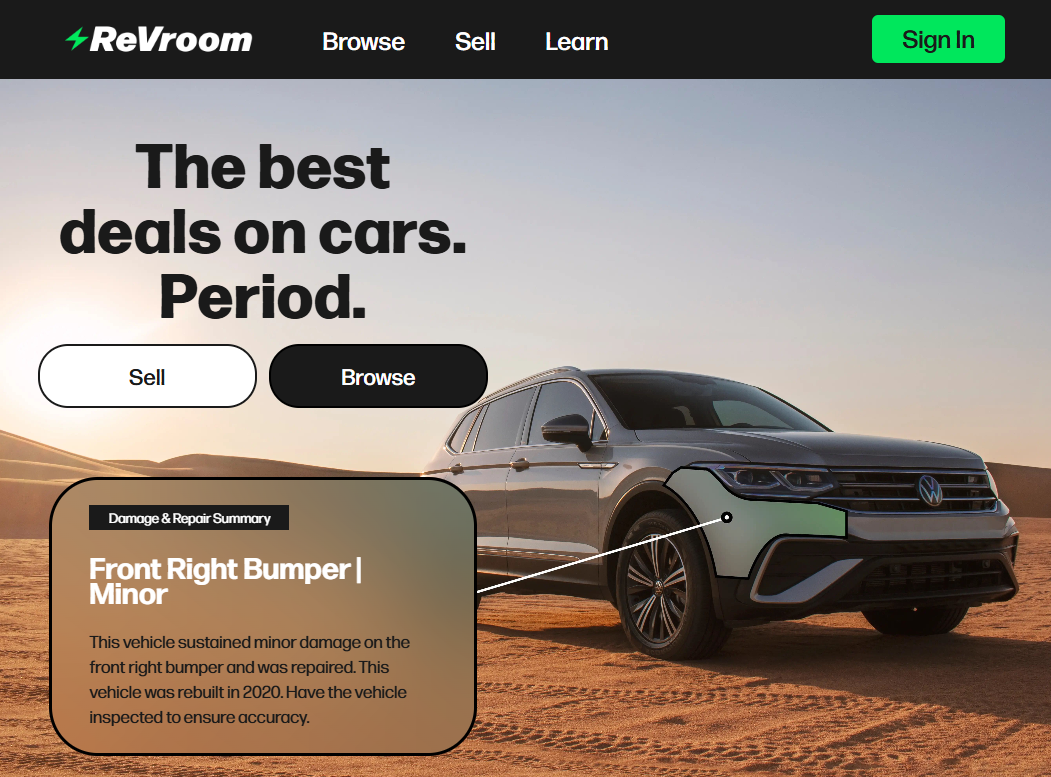
ReVroom is the only marketplace built specifically for rebuilt and branded title vehicles, and the only one where you can filter inventory by history type and by in-house severity grade. Every listing shows the vehicle's history type, its severity grade, and photos of what was repaired, so you know what you are financing before you apply. Want the full picture on one car? A ReVroom Report shows its severity grade, a detailed severity graphic, the estimated savings versus clean-title comps, and where and when it was auctioned. When you know exactly what you are buying, the loan conversation with Navy Federal or any lender gets a lot shorter. Browse rebuilt title cars for sale and find one worth financing.
FAQ
Will Navy Federal finance a rebuilt title vehicle?
Not with its standard auto loan. Navy Federal's published 2026 dealer instructions say the preapproved vehicle loan cannot be used where the title reflects the vehicle as salvaged, lemon, refurbished, or rebuilt, and that members who want one of these cars "will have to qualify for the loan on signature." In plain English, that means a Navy Federal personal loan, which is unsecured and currently runs 8.74% to 18.00% APR. Policies can change, so confirm with a loan officer before you shop.
Will Navy Federal finance a salvage title car?
No. The same dealer instructions list salvaged titles alongside rebuilt ones as ineligible collateral, and a salvage-titled car usually cannot be registered or driven until it is repaired, inspected, and retitled as rebuilt. If you want Navy Federal money on a car with this kind of history, buy one that has already been retitled as rebuilt and finance it with a personal loan.
Does Navy Federal do title loans?
No. Navy Federal does not offer car title loans, and its own education pages warn that title loans can carry rates of 300% per year or more. What it does offer is auto refinancing for eligible vehicles and unsecured personal loans of $250 to $150,000 with no collateral, no fees, and same-day funding in most cases.
What is the 90-day (3-month) title rule for Navy Federal auto loans?
Navy Federal requires a title showing it as first lienholder within 3 months (its FAQ says 90 days) of buying or refinancing a car on a Navy Federal auto loan. If the lien-recorded title is not received in that window, Navy Federal says the loan's APR may be converted to its signature/personal loan rate, which is typically higher. It applies to auto loans only; a rebuilt car bought with a personal loan has no lien, so the rule does not apply.
What interest rate should I expect on a rebuilt title loan?
Through Navy Federal, a rebuilt title purchase is a personal loan, so expect the personal loan range: 8.74% to 18.00% APR for terms up to 36 months and 10.69% to 18.00% for 37 to 60 months, based on credit. For comparison, Navy Federal's clean-title used auto loans start as low as 4.79% APR, and Experian's Q1 2026 data puts the average used-car APR across all lenders at about 11.43%.
Can I get GAP coverage on a rebuilt title vehicle at Navy Federal?
Navy Federal GAP is sold only on Navy Federal auto and motorcycle loans ($499 flat fee, vehicles no older than 7 years), so it does not apply to a rebuilt car financed with a personal loan. Its GAP page does not list rebuilt titles as an exclusion, but since the auto loan itself is not available on a rebuilt title, GAP is effectively off the table. On a personal loan you own the car outright, so the gap between loan balance and car value is yours to manage with a sensible down payment.
How much can I borrow on a Navy Federal personal loan for a car?
Navy Federal's Personal Expense Loan runs from $250 to $150,000, with loans over $50,000 requiring a qualified co-applicant. There is no collateral, no origination fee, no prepayment penalty, and most loans fund in 24 hours or less. Because there is no lien, there is no loan-to-value cap tied to the car.
What are the best alternatives if Navy Federal declines my application?
Local credit unions that use manual underwriting, other lenders' unsecured personal loans, specialty lenders that write rebuilt-title auto loans, and dealer financing programs at rebuilt-title dealerships. Because a rebuilt car costs up to 50% less than its clean-title twin, a modest personal loan or even cash often covers it. Our step-by-step financing guide walks through each path.
Recommended
- Will USAA Finance a Rebuilt Title? Your 2026 Guide
- Can You Finance a Rebuilt Car? Every Lender Type Explained
- Will the Bank Finance a Rebuilt Title? Step-by-Step Guide
- How to Finance Rebuilt Title Cars
- Can a Bank Finance a Rebuilt Title? What Buyers Must Know
- What Insurance Companies Cover Rebuilt Title Cars?
