


USAA Rebuilt Title Insurance: Will USAA Insure a Rebuilt Title? (2026)
May 4, 2026
Short answer: yes, in most reported cases. USAA is commonly reported to insure a rebuilt title car once it has been repaired, passed its state safety inspection, and been issued a rebuilt title. It is decided case by case, it varies by state, and a car still sitting on a salvage title does not qualify with USAA or anyone else. Liability is the easy part. Full coverage is possible but not promised. Here is how to walk in prepared.
TL;DR:
- Rebuilt title cars can often be insured with USAA after passing inspection and receiving a rebuilt title, with decisions made case by case.
- Coverage options include liability, and possibly comprehensive and collision, but are case-dependent.
- Proper documentation and persistence are essential for securing insurance and acceptable premiums.
You’ve found a great rebuilt title car at a price that actually fits your budget, and now you’re wondering if USAA will cover it. Here’s the thing: most people assume rebuilt title vehicles are nearly impossible to insure, especially with a major carrier like USAA. That assumption has scared off plenty of perfectly good buyers from perfectly good cars. The reality is more nuanced, more navigable, and honestly more encouraging than the internet would have you believe. Let’s clear the air, walk through what USAA actually looks for, and give you a practical roadmap for getting covered.
One more prep tip before you call: insurers respond well to documentation, and so should you. A ReVroom Report gives you in-house severity grading, a detailed severity graphic, and a check of how the price stacks up against the whole market — useful for your own decision and handy backup when the underwriter asks what happened to the car.
Table of Contents
- Understanding rebuilt titles vs salvage titles
- Can you get USAA insurance on a rebuilt title car?
- Will USAA insure a salvage title car?
- What documentation and inspections does USAA require?
- Coverage types and limitations for rebuilt title cars
- How much does USAA rebuilt title insurance cost?
- Does USAA finance rebuilt titles?
- What most buyers overlook about USAA and rebuilt title insurance
- Looking for affordable, reliable rebuilt title options and insurance help?
- Frequently asked questions
Key Takeaways
| Point | Details |
|---|---|
| Rebuilt vs. salvage | Rebuilt titles can be insured. A car still on a salvage title generally cannot be, with USAA or any other major insurer, because it is not legal to drive yet. |
| Documentation is critical | Proof of ownership, inspection reports, and rebuilt title paperwork are needed for USAA insurance approval. |
| Coverage varies | USAA may offer liability or broader coverage depending on inspection results, but it’s not guaranteed. |
| Cost and payout | No published rebuilt rate. Premiums can run a little higher, and a total-loss payout tracks rebuilt-market value, so pay a fair rebuilt price for the car. |
| Direct contact matters | Call or email USAA with your full documentation for case-specific decisions and written confirmation. |
| Compare before you buy | Quotes beat lists. Get two or three quotes on the same VIN and use a checklist to confirm the car meets safety and insurance eligibility. |
Understanding rebuilt titles vs salvage titles
Short answer: a salvage title means the car was declared a total loss and is not yet road-legal; a rebuilt title means it has since been repaired, inspected by the state, and cleared to drive. Insurers, USAA included, treat those two documents completely differently.
To separate fact from myth, it’s essential to first understand what makes a vehicle’s history impact your ability to get insurance. These two titles get mixed up all the time, and that confusion costs buyers real money and real opportunities.
A vehicle receives a salvage title when an insurance company declares it a total loss, meaning the estimated repair cost exceeded a certain percentage of the car’s market value. At that point, the car carries a title that marks it as not road-legal and not insurable for driving purposes. You simply cannot put plates on it, drive it legally, or get standard auto insurance on it in that state. As US News notes, you generally cannot insure a vehicle while it holds a salvage title because it is not legally drivable.
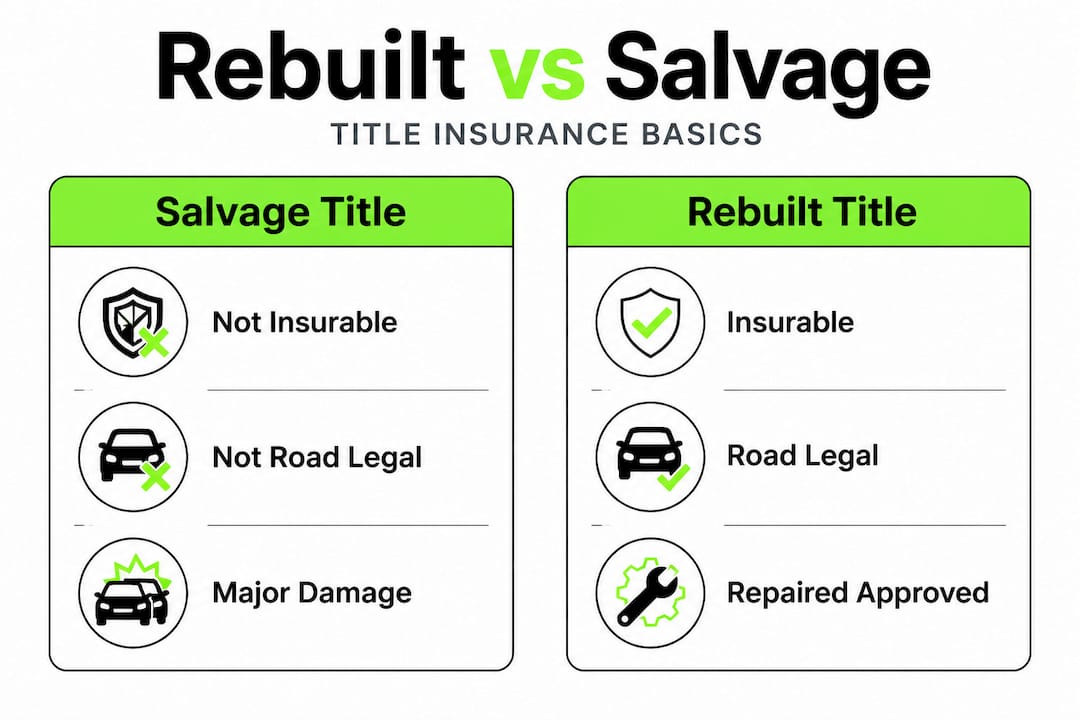
A rebuilt title, on the other hand, is a completely different document. It is issued by a state DMV after a vehicle has been professionally repaired and passed a state-mandated safety inspection. Once a car receives a rebuilt title, it is legally road-worthy. It can be registered, licensed, plated, and yes, insured. Understanding the salvage to rebuilt process makes this journey a lot less mysterious.
Here is a quick side-by-side to make this crystal clear:
| Feature | Salvage title | Rebuilt title |
|---|---|---|
| Road legal | No | Yes |
| Can be insured | Typically no | Yes, varies by insurer |
| State inspection required | Not yet | Yes, completed |
| Eligible for registration | No | Yes |
| Eligible for USAA coverage | Generally no | Commonly reported yes, case by case |
The single most common mistake buyers make is assuming these two categories are interchangeable. They are not. Insurance companies, including USAA, make their decisions based on this distinction. If your car has already received its rebuilt title and passed inspection, you are starting from a completely different position than someone trying to insure a car that has not yet been through that process.
A few other missteps to watch out for:
- Assuming the title type alone guarantees or disqualifies coverage
- Forgetting to gather repair documentation before calling your insurer
- Expecting the same coverage limits and premiums as a clean title vehicle
Understanding the title distinction is your starting line. Everything else follows from there.
Can you get USAA insurance on a rebuilt title car?
Short answer: commonly reported yes, once the car has its rebuilt title in hand. Liability is the usual starting point; comprehensive and collision are decided case by case after USAA reviews your paperwork.
Now that you know the paperwork difference, you can focus on how USAA and similar insurers actually treat rebuilt title cars. And here is where things get interesting.
USAA, like every major insurer, does not write a standard driving policy on a car that still holds a salvage title. But USAA coverage for rebuilt title vehicles is regularly reported to become available once the vehicle has been repaired, inspected, and officially received a rebuilt title. That is the threshold. Cross it with your paperwork in order, and the conversation changes.
What you will not find is a clean, publicly posted USAA underwriting policy for rebuilt titles. Searching for one turns up third-party Q&A content rather than an official rulebook. This is not a red flag; it simply means the decisions happen case by case, based on internal review of your vehicle’s documentation and condition. Expect variability. Expect questions. Expect the process to take some back and forth.
Here is what coverage typically looks like for rebuilt title vehicles with USAA:
- Liability coverage is the most common starting point. This covers damage you cause to others and is the easiest type to obtain for a rebuilt title vehicle.
- Comprehensive coverage (theft, weather, non-collision events) may be available depending on the vehicle’s condition and documentation provided.
- Collision coverage is possible but less consistent. It depends heavily on the inspection results and what the underwriter decides.
- Full coverage combining liability, comprehensive, and collision is the hardest to lock in and is never guaranteed.
To see how USAA’s reported stance compares with the other big names, our roundup of which insurance companies cover rebuilt title cars lines them up side by side. And speaking of calling, that is exactly what you should do. Contact USAA directly with your VIN and full documentation ready before assuming anything.
Pro Tip: Do not just ask “Can you insure my rebuilt title car?” Ask specifically what types of coverage are available for your vehicle’s VIN, your state, and your documentation. The more specific your question, the more useful the answer.
There is also a broader picture worth seeing here. USAA is just one option. You can explore all of your rebuilt title insurance options to compare how different providers approach this. Some are reported to be more flexible than USAA. Some are less. Shopping around is always smart, and if you are hunting for the lowest premium, start with our guide to the cheapest insurance for a rebuilt title.
Will USAA insure a salvage title car?
Short answer: generally no, and neither will any other major insurer, because a salvage-titled car is not legal to drive. Get it repaired, inspected, and retitled as rebuilt first. Then USAA is commonly reported to consider it.
This is the question that trips up more buyers than any other, so it deserves its own plain answer. A salvage title is a parked-car document. The state has not cleared the vehicle for the road, so there is nothing for a driving policy to cover. Some insurers will write a limited comprehensive-only policy on a salvage car sitting in storage, but that is a different product from the auto policy you are picturing, and it is not something to count on.
The path forward is the same in every state: complete the repairs, pass the state safety inspection, receive the rebuilt title, and then call. If you are shopping, this is also the simplest reason to buy a car that has already been retitled as rebuilt instead of a salvage car you would retitle yourself. The inspection is already done, the paperwork already exists, and the insurance conversation starts on day one. Our walkthrough of how rebuilt cars are retitled shows exactly what that process involves.
What documentation and inspections does USAA require?
Short answer: the rebuilt title certificate, the state inspection certificate, current registration, and repair records from a licensed shop. USAA may also ask for its own inspection before extending comprehensive or collision.
Understanding USAA’s general stance helps, but the right paperwork is genuinely make-or-break when seeking coverage. This is where a lot of buyers drop the ball, not because they lack the right car, but because they show up to the conversation unprepared.
Multiple sources confirm that you may need to provide documentation and a vehicle inspection to insure a rebuilt title vehicle with USAA. Here is what you should have ready before you pick up the phone:
- Proof of ownership: Your name on the title, clear and current.
- Vehicle registration: Current registration in your state.
- Rebuilt title certificate: The actual title document issued after inspection, not any prior version.
- Repair documentation: Records from a licensed mechanic or body shop showing what work was performed.
- State inspection certificate: The official result of your state’s safety inspection that triggered the rebuilt title issuance.
- Photos of completed repairs: Before-and-after documentation of the vehicle’s condition.
USAA may also require an independent inspection of their own before granting broader coverage like collision or comprehensive. This is not unusual and not a reason to panic. It is their way of verifying the vehicle is in the condition you say it is.
Understanding the rebuilt title retitling process in your state is important here because requirements vary. What satisfies an inspector in Texas may differ from what is required in Ohio. Make sure the documentation you have is state-specific and complete.
A few common bureaucratic stumbling blocks buyers run into:
- Missing repair receipts because they assumed verbal confirmation was enough
- Submitting an outdated title version instead of the rebuilt title certificate
- Not having the inspection certificate separate from the title document itself
- Providing incomplete repair records that skip certain work that was done
Pro Tip: Scan every document related to your vehicle’s repair history and save it in a dedicated folder, both on your device and in the cloud. Name each file clearly (for example: “rebuilt-title-certificate-2023-honda-civic.pdf”). When USAA or any insurer asks for documentation, you can send it immediately without scrambling. Speed and organization signal that you are a prepared, low-risk client.
Want a structured way to approach this? The inspection checklist for rebuilt cars at ReVroom is built exactly for this kind of preparation.
Coverage types and limitations for rebuilt title cars
Short answer: liability is the most consistently available; comprehensive and collision are possible but case by case; and any total-loss payout is based on rebuilt-market value, not clean-title value.
Once your paperwork is organized and you are ready to submit, it is important to know what kind of protection you can realistically expect. Let us be straight with you here, because honest expectations are more useful than wishful thinking.
As WalletHub’s analysis reports, coverage for rebuilt title vehicles with USAA only becomes a possibility after the car has been fully repaired, inspected, and issued a rebuilt title. From there, here is what the coverage landscape typically looks like:
- Liability only: The most consistently available option. Covers third-party property damage and bodily injury you cause in an accident.
- Comprehensive: Available in many cases but not guaranteed. Covers non-collision events like hail, theft, or fire.
- Collision: Possible but often the hardest to unlock. Covers your vehicle in a collision regardless of fault.
- Full coverage: The full package is available in some cases but depends heavily on the vehicle, repair quality, and underwriter discretion.
There are also real limitations to keep in mind:
“Rebuilt title cars may face higher premiums, coverage exclusions related to prior vehicle history, or outright denial of certain coverage types depending on the insurer’s internal review process.”
That is not a reason to walk away. It is a reason to go in with eyes open. Premiums on rebuilt title vehicles can run higher than on comparable clean title cars because insurers factor in the vehicle’s history and a potentially lower resale value. You are still likely paying far less overall when you consider that rebuilt title cars are often priced up to 50% below their clean title equivalents.
It is also worth noting that payout amounts in a total loss scenario may reflect the rebuilt title market value, which is lower than a clean title equivalent. This is exactly why paying a fair rebuilt-market price for the car matters: buy at that value and the compensation matches what you spent. Discuss it with your insurer before you commit, not after. Learn more about the full picture of rebuilt car insurance details so you can budget accordingly.
How much does USAA rebuilt title insurance cost?
Short answer: USAA does not publish a rebuilt title rate. Liability-only premiums are commonly reported to land close to what a clean-title car pays, while full coverage can cost more or come with limits, because the car is insured at its rebuilt-market value. The only real number is the quote on your VIN.
Think of it like insuring a house with a documented old roof repair. The premium is driven mostly by the same things as any other policy: your driving record, your state, your zip code, the car’s make and model, and the coverage you pick. The rebuilt brand is one more input, and how much weight it gets depends on the underwriter looking at your file.
Three things move the number in your favor:
- Documentation. A complete repair file and a passed state inspection give the underwriter fewer unknowns to price in.
- Coverage choice. If full coverage comes back expensive or limited, liability plus comprehensive is a common middle ground for an older, lower-value car.
- Purchase price. Because a total-loss payout tracks rebuilt-market value, paying a fair rebuilt price for the car is what keeps the payout in line with what you spent. A ReVroom Report shows how a listing’s price stacks up against the whole market, which is the cheapest insurance math you will ever do.
Quotes beat lists. Get two or three quotes on the same VIN, ask each insurer the same questions, and compare. Our guide to the cheapest insurance for a rebuilt title gives you the question list to use on every call.
Compare rebuilt title insurance quotes
Insuring a rebuilt title car is easier than most people expect.
Answer a few questions once and see quotes from multiple insurers side by side in a few minutes. Waiting on a USAA quote? Having a few others next to it is an easy way to see how it stacks up, and shopping around is usually where the savings show up.
Compare my quotes →Sponsored · Insurify
Does USAA finance rebuilt titles?
Short answer: it is commonly reported as case by case, and plenty of members report being declined or offered a smaller loan on a rebuilt title car than on a clean-title one. Insuring and financing are two different desks at USAA, and a yes from one is not a yes from the other.
Buyers often assume that if USAA will insure the car, USAA will also lend on it. Lender policy is stricter, because the loan is secured by the car’s resale value and a rebuilt brand lowers that value. Ask the loan desk directly, with the VIN, before you count on it, and have a backup lender ready. Credit unions and specialty lenders are reported to be more flexible on rebuilt titles. We cover the reports, the workarounds, and what to ask in Will USAA finance a rebuilt title? and the broader can you finance a rebuilt car guide.
What most buyers overlook about USAA and rebuilt title insurance
Short answer: there is no rulebook, so your records and your persistence decide the outcome as much as the car does. Get every answer in writing.
Here is the honest, been-around-the-block take: most buyers underestimate just how variable insurer rules are for rebuilt title vehicles. They search online, find a few articles, and assume the experience will follow a predictable script. It often does not.
There is no published USAA underwriting rulebook for rebuilt titles. That means the front-line representative you speak with may not have crystal-clear guidance either. We have seen buyers call three times and get three different answers. That is not a knock on USAA specifically; it reflects the reality that rebuilt title underwriting is handled case by case, with a lot of discretion left to individual reviewers.
What this means practically: your persistence and your records matter as much as the car itself. A buyer with a spotless documentation folder who follows up consistently will move through this process faster and with better results than someone who calls once, gets discouraged, and gives up. The car did not change. The outcome did.
Here is the other thing most buyers miss: a rebuilt title is not a magic key that unlocks any specific coverage level. The quality of the repairs, your state’s inspection standards, the vehicle’s make and model, and the specific underwriter reviewing your file all factor in. Two people with the same car in the same state can get different answers. That is just the reality of navigating real-world insurance challenges for rebuilt vehicles.
The takeaway? Never assume eligibility. Never assume denial either. Get confirmation in writing, or at the very minimum document the date, time, and name of the representative you spoke with. Treat this like the financial decision it is, because it is.
Looking for affordable, reliable rebuilt title options and insurance help?
If you are ready to apply these tips and shop with confidence, ReVroom was built for exactly this moment.
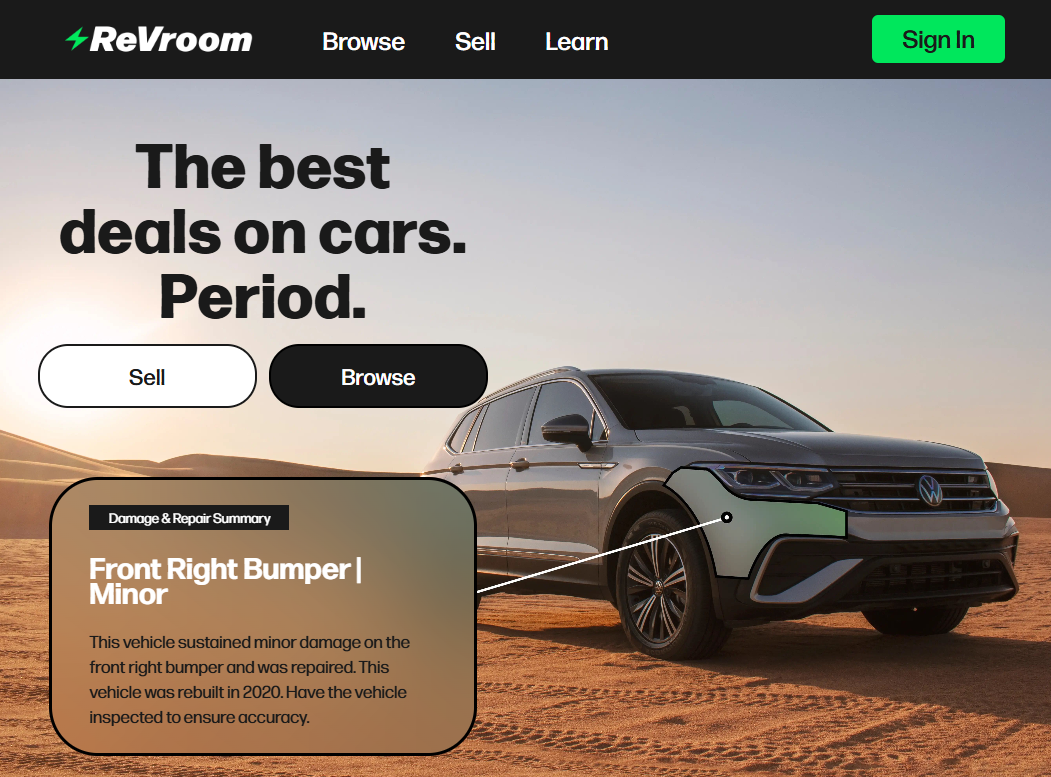
ReVroom is the only online marketplace built specifically for affordable rebuilt vehicles, and the platform is designed to give you the transparency you need before you ever call an insurance company. It is the only site where you can filter inventory by history type, from hail and cosmetic paint chips all the way to fire, and by in-house severity grade, and every listing shows photos of what was repaired. That kind of upfront documentation is also exactly what insurers like USAA want to see. And for a car listed anywhere else, a ReVroom Report gives you the same upfront clarity before you commit. Ready to find a vehicle you can feel great about and insure with confidence? Browse rebuilt title cars and start there. Better car. Smarter buy. Go further.
Frequently asked questions
Will USAA insure a rebuilt title car?
USAA is commonly reported to insure rebuilt title cars once the vehicle has been repaired, passed its state inspection, and been issued a rebuilt title. Decisions are made case by case and vary by state and by the documentation you provide. USAA does not publish a public underwriting rule for rebuilt titles, so get the answer for your VIN in writing.
Will USAA insure a salvage title car?
Generally no. A car that still carries a salvage title is not legal to drive, so USAA and other major insurers do not write a standard driving policy on it. The car has to be repaired, pass the state inspection, and receive a rebuilt title first. After that, the conversation changes.
How much does USAA rebuilt title insurance cost?
USAA does not publish a rebuilt title rate. Liability-only premiums are commonly reported to land close to clean-title pricing, while full coverage can cost more or be limited because the insured value is the rebuilt-market value, not the clean-title value. Get quotes from two or three insurers on the same VIN and compare.
Does USAA finance rebuilt titles?
USAA auto loans on rebuilt title cars are commonly reported as case by case, and many members report being declined or offered a smaller loan than on a clean-title car. Lender policy is separate from insurance policy, so ask the loan desk directly and have a backup lender ready.
Can I get full coverage from USAA on a rebuilt title car?
Comprehensive and collision coverage on a rebuilt title car may be available, but it is not guaranteed and depends on the underwriting review, your state, and your documentation.
What paperwork do I need for USAA rebuilt title insurance?
Proof of ownership, current registration, the rebuilt title certificate, the state inspection certificate, and repair records from a licensed shop. Photos of the completed repairs help.
Are premiums higher for rebuilt title cars?
They can be somewhat higher than on a comparable clean title car, because insurers account for the vehicle’s history and a lower market value. Buying at a fair rebuilt-market price keeps a total-loss payout in line with what you paid.
Does USAA publish a public underwriting policy for rebuilt titles?
No. There is no official underwriting guide from USAA for rebuilt title vehicles. Most information online comes from member reports and third-party sources, which is why written confirmation for your specific car matters.
Already financed your rebuilt title car?
If your credit has improved since you bought, a refinance can lower the payment on the same car. One application, up to 4 offers.
See if a refinance lowers your payment →Sponsored · myAutoloan
